


Train Your Team on the New UAE VAT Rules: A 2-Hour Session From AED 250/Hour
Last updated: 6 October 2026. UAE VAT and e-invoicing dates reflect Ministry of Finance and Federal Tax Authority publications as of this date. · By the Business Setup and VAT Compliance team, Mussafah M4, Abu Dhabi
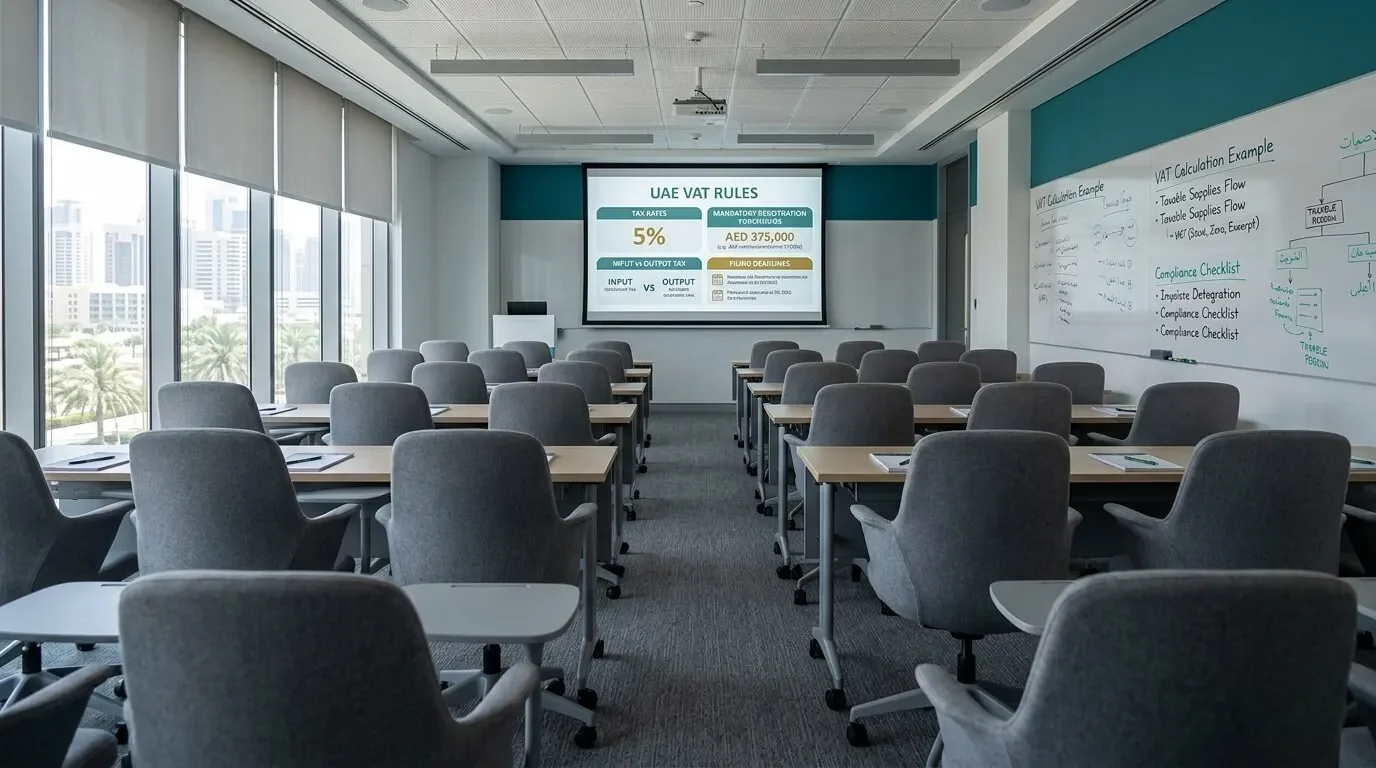
Quick answer: Most of the UAE VAT amendments in Cabinet Decision No. 149 of 2026 apply from 1 October 2026. The three your team must understand first are: input VAT can be blocked on cash payments above a threshold the Minister of Finance has not yet published; input VAT recovery now depends on documented supplier and supply verification under FTA Decision No. 13 of 2026; and VAT on staff housing is recoverable through the labour-law exception only where MoHRE makes the housing mandatory. Book the 49-seat training room in Musaffah from AED 250/hour and run the two-hour agenda in this post.
The UAE changed its VAT rulebook twice in twelve months, and the second round landed on 1 October 2026 — the same week most businesses were finalising their September quarter VAT return. If the only person in your company who understands the new input tax rules is the person who signed the VAT registration, you have a single point of failure in the middle of your finance function.
This post does two things. First, it sets out what actually changed, in the order your team will meet it, with the instrument, the effective date and the practical consequence for each change. Second, it gives you a two-hour session agenda you can run in a rented training room in Mussafah, with the cost per head worked out so you can compare it against the first penalty you would otherwise pay.
Key takeaways
- Cabinet Decision No. 149 of 2026 was issued on 1 September 2026 and most of it applies from 1 October 2026
- Input VAT on a supply paid, or intended to be paid, in cash above a Ministerial threshold is not recoverable — the threshold is still to be published
- Supplier and supply verification is now a documented duty under FTA Decision No. 13 of 2026, and the FTA can deny recovery where a supply is connected to tax evasion
- The revised input tax apportionment method is deferred to the first tax year starting after 1 October 2027
- E-invoicing is mandatory from 1 January 2027 for businesses with revenue of AED 50 million or more, and from 1 July 2027 for the rest
- A two-hour session in the Musaffah training room costs AED 500 from AED 250/hour — about AED 10.20 per head at full capacity of 49
What changed on 1 October 2026
Nothing about the headline rate moved. UAE VAT is still charged at 5%, and the mandatory registration threshold is still AED 375,000 of taxable supplies in a twelve-month period. What moved is the machinery around input tax recovery, verification and invoicing — and that machinery is where penalties live.
| Instrument | What it changes | Applies from |
|---|---|---|
| Cabinet Decision No. 149 of 2026 | Amends the Executive Regulation of Federal Decree-Law No. 8 of 2017 on VAT: composite supplies, the profit margin scheme, employee accommodation and benefits, cash payments, medical products, the Capital Assets Scheme and tax credit notes. | 1 October 2026, except input tax apportionment, which starts in the first tax year beginning after 1 October 2027 |
| FTA Decision No. 13 of 2026 | Sets the due-diligence measures for Article 54 bis of the VAT Law: supplier verification and supply verification, with input VAT recovery denied where a supply is connected to tax evasion. | 1 October 2026 |
| Federal Decree-Law No. 16 of 2025 | Amends the VAT Law itself, including the Article 54 bis anti-evasion provision that Decision No. 13 now polices. | 1 January 2026 |
| Federal Decree-Law No. 17 of 2025 | Rewrites the Tax Procedures Law: tighter deadlines and broader Federal Tax Authority powers. | 1 January 2026 |
| Ministerial Decisions Nos. 243 and 244 of 2025 | Establish the mandatory Electronic Invoicing System and its phased implementation, with an Accredited Service Provider at the centre of every exchange. | Pilot and voluntary from 1 July 2026; mandatory in phases from 1 January 2027 |
Two of those instruments deserve a warning label. Cabinet Decision No. 149 of 2026 is a technical amendment to the Executive Regulation, but it touches the moment a purchase becomes recoverable. FTA Decision No. 13 of 2026 is narrower and sharper: it turns what used to be good practice into a duty, and it gives the Federal Tax Authority a route to refuse input VAT recovery altogether.
The Federal Tax Authority has also been explicit that the changes are part of a broader shift in administration — recovery is becoming more controlled, more procedural and more evidence-driven. That phrase matters for a training session, because it tells your team what the auditor will be looking for: not just the invoice, but the reasoning behind the transaction.
The eight rules your team needs to know
These are the eight changes most likely to surface in an ordinary month of purchasing, payments and payroll. Each is short enough to fit on a slide, and each has a question your team should be able to answer by the end of the session.
1. Cash payments can block input VAT recovery
A new clause in Article 54 of the Executive Regulation removes input VAT recovery where the value of a supply exceeds an amount to be set by the Minister of Finance and the consideration is paid, or intended to be paid, in cash. The Ministry's stated purpose is to strengthen compliance and mitigate the risk of tax evasion.
Two things to tell your team. First, the threshold had not been published as of 6 October 2026, and a separate Ministerial Decision will set the amount and the controls around it, including whether it applies per invoice, per supplier or per tax period. Second, the rule rewards a habit your team can adopt today: pay suppliers from the corporate account, and where a cash payment is genuinely unavoidable, document why.
2. Supplier verification is now a documented duty
Under FTA Decision No. 13 of 2026, supplier verification is carried out the first time you deal with a supplier, and repeated if twelve months have passed. It means checking identity documentation against official databases, verifying the individual authorised to represent the supplier, and confirming the supplier has an actual place of business consistent with its claimed activity.
On top of that, your team must assess three prescribed risk indicators: a change of address, a change of key personnel, and transactions that are disproportionate to the size and history of the business. Any one of them should trigger a closer look, not a silent approval.
3. Every supply needs its own check
Supply verification is the more demanding half, because it applies to every individual supply you receive, not just to the supplier as a whole. Your team must be able to confirm that the supplier's participation rests on genuine commercial reasons, that pricing and margins are not commercially unjustifiable, that the goods or services fall within the supplier's licensed activities, and that the title and origin of the goods are sound.
Where annual supplies from a single supplier exceed AED 375,000, the checks go further: you must obtain unqualified written confirmation from a bank authorised in the UAE that the supplier holds an account there, and review public reviews and media coverage of that supplier. Do not confuse this with the AED 375,000 mandatory VAT registration threshold — the two numbers coincide, but one is a registration trigger and the other is a verification trigger, and mixing them up in a training session is exactly the kind of error the new rules are designed to catch.
The reason this matters financially is Article 54 bis of the VAT Law, inserted by Federal Decree-Law No. 16 of 2025. The Federal Tax Authority can deny input VAT recovery where a supply formed part of a chain of supplies connected to tax evasion. If the recipient knew of the connection, rejection is mandatory. If the recipient should have known, the outcome is the same in practice.
4. Staff housing follows the MoHRE mandate
Input VAT on accommodation provided to employees is recoverable through the labour-law exception only where a Ministry of Human Resources and Emiratisation decision or directive makes the housing mandatory. For other employee benefits provided under a contract or a documented policy, recovery follows the cases and conditions the Federal Tax Authority sets, and the amendments give the Authority greater discretion to define those conditions.
The practical instruction for your HR and finance teams is to review employment contracts, HR policies and accommodation arrangements — and the written rationale behind each benefit — before recovering the input tax, rather than after the Federal Tax Authority asks for it.
5. Bundles are taxed by their substance
A new provision in Article 4 of the Executive Regulation clarifies the VAT treatment of supplies comprising multiple components. A single composite supply is now taxed in line with the economic substance of the supply as a whole, rather than being split into parts that happen to carry different rates.
If your business sells bundled packages — a licence with a year of virtual office, a course with materials, a service with setup — the VAT treatment of the bundle should be reassessed and written down, because the answer is no longer a matter of preference.
6. The Capital Assets Scheme has an AED 5 million line
The amendments confirm an AED 5 million VAT-exclusive threshold for assets that fall within the Capital Assets Scheme, and clarify the scheme's scope so that it stays consistent with the VAT Law. For most small and mid-sized businesses this is a boundary rule rather than a daily one, but it belongs in the session because it decides how a large purchase is adjusted over time rather than in the period it was made.
7. Partial exemption moves to a turnover test — later
Under the revised Article 55, the recovery percentage for residual input tax is calculated by comparing the value of supplies that carry a right to recovery with the total value of all supplies, rounded to the nearest whole number, and applying that percentage to residual input tax. That is a shift from the existing input-based calculation to an output-based one, and it affects businesses making both taxable and exempt supplies — financial institutions, real estate businesses, investment structures and certain holding companies among them.
The change has been deliberately deferred: it applies from the first tax year commencing after 1 October 2027, not from 1 October 2026. Government entities and charities keep a separate calculation based on the ratio of recoverable input tax to total recoverable and non-recoverable input tax. A worked illustration of the new method: a company with AED 8 million of taxable supplies and AED 2 million of exempt residential rent in a tax year has a recovery percentage of 80%, so AED 80,000 of AED 100,000 of residual input tax is recoverable.
8. Old VAT credits are expiring
Federal Decree-Law No. 17 of 2025 rewrote the Tax Procedures Law with effect from 1 January 2026, and one of its most consequential changes is the five-year window on tax credits. Input VAT credits more than five years old are gone, and the clock starts at the end of the tax period in which the credit arose. A business that overpaid VAT in the first quarter of 2021 had until the first quarter of 2026 to claim it back; credits from later 2021 continue to expire through the year.
The same law removed the requirement to issue a self-directed tax invoice for reverse charge transactions, which is a small but welcome simplification for businesses importing services. Both changes belong in the session, because they answer the two questions staff ask most: how long do we have, and what paperwork do we still need.
The e-invoicing timeline your team should memorise
Electronic invoicing is the change most likely to be handled by the wrong person at the wrong time, because it is not a VAT-rate question and it does not wait for a VAT registration. Under Ministerial Decisions Nos. 243 and 244 of 2025, e-invoicing is mandatory for any person conducting business in the UAE, regardless of VAT registration status, unless specifically excluded. Both the issuer and the recipient must appoint an Accredited Service Provider, and invoices and credit notes must be exchanged in a structured format through that provider.
The programme opened with a pilot and voluntary onboarding on 1 July 2026. Mandatory implementation is then phased by annual revenue, as set out below.
| Phase | Who is in scope | Appoint an ASP by | Mandatory from |
|---|---|---|---|
| Pilot and voluntary | Any business that opts in | From 1 July 2026 | Voluntary |
| Phase 1 | Annual revenue of AED 50 million or more | 31 July 2026 | 1 January 2027 |
| Phase 2 | Annual revenue below AED 50 million | 31 March 2027 | 1 July 2027 |
| Phase 3 | Government entities | 31 March 2027 | 1 October 2027 |
One clarification worth repeating in a session: an unstructured PDF, a Word document, an image, a scanned copy or an email attachment is not an e-invoice. The exchange has to be structured data, transmitted through an Accredited Service Provider and reported to the Federal Tax Authority. Businesses that assume their existing accounting export is enough are the ones who will discover the gap in the first quarter of 2027.
What the penalties look like
Penalties are the cheapest argument for training. The two tables below are the ones your team should see side by side, because one set is administered by the Federal Tax Authority under the VAT framework and the other under the e-invoicing framework — and both are triggered by process failures, not by intent.
| VAT penalty | Amount |
|---|---|
| Failure to register for VAT | AED 20,000 |
| Late filing of a tax return | AED 1,000 to AED 4,000 per return |
| Late payment of tax | 2% to 14% of the unpaid tax |
| Incorrect record keeping | AED 10,000 |
| Tax evasion | Up to AED 1,000,000 or more |
| E-invoicing violation | Administrative penalty |
|---|---|
| Failure to implement the system, including failure to appoint an Accredited Service Provider in time | AED 5,000 for each month, or part of a month, of delay |
| Failure to issue and transmit an electronic invoice | AED 100 per invoice, capped at AED 5,000 per calendar month |
| Failure to issue and transmit an electronic credit note | AED 100 per credit note, capped at AED 5,000 per calendar month |
| Failure to notify the Authority of a system failure | AED 1,000 for each day, or part of a day, of delay |
| Failure to notify the Authority of changes to registered data | AED 1,000 for each day, or part of a day, of delay |
Read the e-invoicing table carefully. The AED 100 per invoice penalty is capped at AED 5,000 per calendar month, but the failure-to-implement penalty is AED 5,000 for each month or part of a month with no cap stated, and the system-failure notification penalties are AED 1,000 for each day or part of a day. A company that misses its phase date and then discovers a system fault in the same quarter can accumulate penalties faster than the training would have cost it.
The two-hour session agenda
Two hours is long enough to cover the rules and short enough that a manager will actually release the team for it. The agenda below is built for a projector and a whiteboard, which is what the Musaffah training room provides, and it ends with a written output rather than a slide deck.
| Time | Module | What your team should be able to do afterwards |
|---|---|---|
| 0:00 – 0:20 | What changed, and why | Name the five instruments above and the date each one applies from. |
| 0:20 – 0:45 | Cash payments and blocked input VAT | List every supplier the business pays in cash, and flag them for a payment-method review. |
| 0:45 – 1:10 | Supplier and supply verification | Run the three risk indicators and apply the AED 375,000 bank-confirmation test correctly. |
| 1:10 – 1:35 | E-invoicing phases and penalties | State the company's phase date, its ASP appointment deadline and the penalty for missing it. |
| 1:35 – 2:00 | Write the policy before you leave | Draft a one-page purchasing, payment and verification policy the team will actually use. |
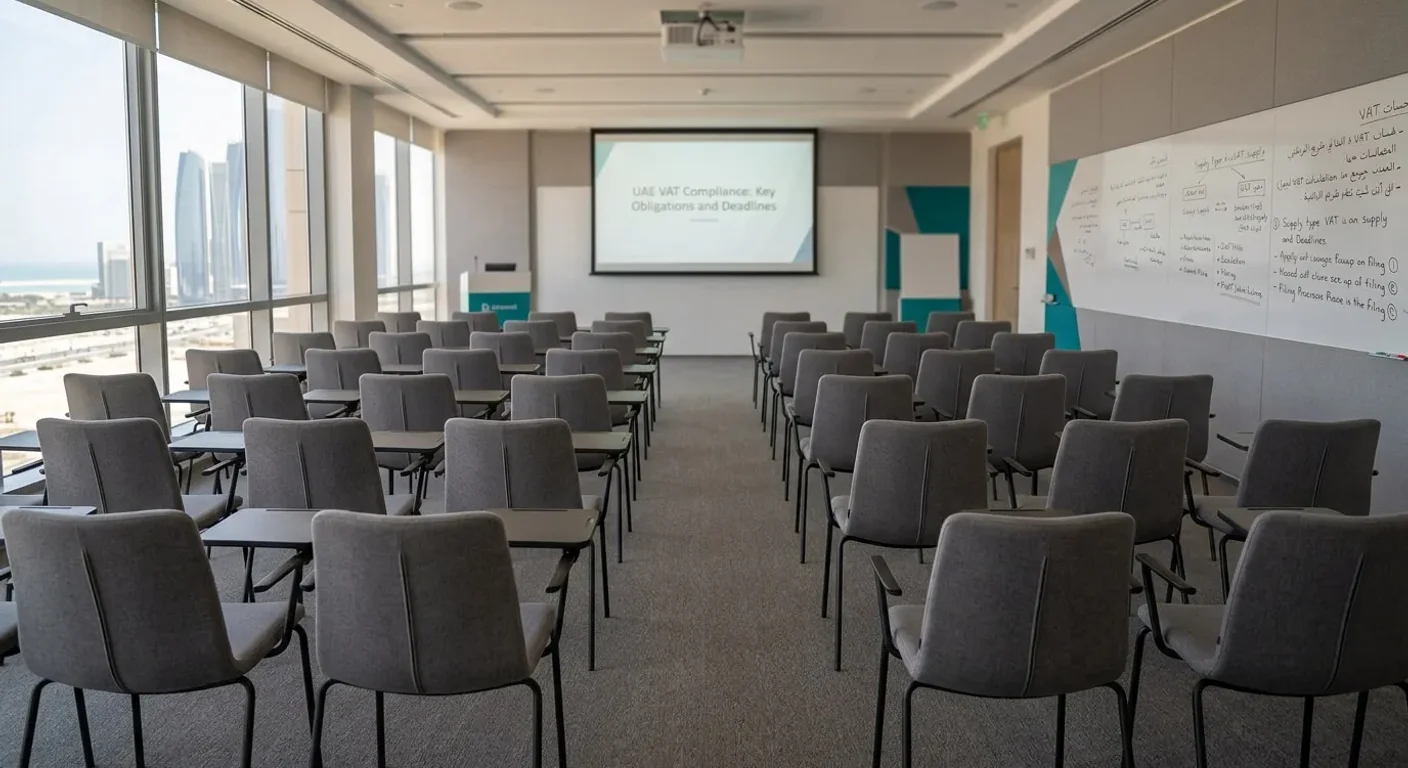
The last twenty minutes are the ones that decide whether the session was worth booking. Have every attendee write down the three suppliers the business pays in cash, the three suppliers whose annual spend exceeds AED 375,000, and the date the company must appoint an Accredited Service Provider. If the group cannot fill in all three, the session has found the gap — and that is the deliverable, not the presentation.
What the session costs, per head
The 49-person training room in Mussafah M4, Block 10, starts from AED 250 per hour, with projector, air conditioning, high-speed WiFi and a whiteboard included, and seating for up to 49. Hourly booking is available and same-day booking can be arranged on request.
| Session length | Total from AED 250/hour | Per head at 49 seats | Per head at 20 attendees |
|---|---|---|---|
| 1 hour | AED 250 | AED 5.10 | AED 12.50 |
| 2 hours | AED 500 | AED 10.20 | AED 25.00 |
| 3 hours | AED 750 | AED 15.31 | AED 37.50 |
| Half day (4 hours) | AED 1,000 | AED 20.41 | AED 50.00 |
The comparison that matters is not against another venue. It is against the first penalty you would otherwise pay. A single late-filed VAT return costs between AED 1,000 and AED 4,000; a failure to register costs AED 20,000. One avoided late-filing penalty pays for between roughly four and eight two-hour sessions in the Musaffah room, and one avoided registration penalty pays for forty of them.
Compare that with the alternatives. A hotel meeting room in Abu Dhabi is typically quoted by the day with a minimum spend and a catering condition attached, and it buys you a location your team does not need for a compliance briefing. Renting by the hour converts a fixed cost into a variable one, so you pay for the two hours you use and nothing else. If your group is smaller than twenty, a meeting room rental in Abu Dhabi may be the better fit; if it is a full-day programme, see our training room rental cost guide and our post on renting a Musaffah training room by the hour instead of buying space.
Catering, printing and stationery are not part of the hourly rate, so budget for them separately if you are running a half-day session.
Before, during and after the session
A training session without a follow-up is an afternoon, not a control. Run the checklist below and the room booking turns into a compliance artefact you can point to.
- Before: pull your supplier list and mark every payment method. Cash-paid suppliers go on the review list.
- Before: list suppliers whose annual spend exceeds AED 375,000 and check whether you hold the bank confirmation for each of them.
- Before: confirm your annual revenue band so everyone knows which e-invoicing phase date and ASP deadline applies to the company.
- Before: print the agenda and the penalties tables. Do not rely on the projector alone.
- During: open with the instrument table, not with the law. Staff remember dates and consequences; they do not remember article numbers.
- During: run the three risk indicators against a real supplier the team already knows, so the check is concrete rather than theoretical.
- During: walk through one composite supply the business actually sells, and agree its VAT treatment out loud.
- During: check whether any input VAT credits from 2021 remain unclaimed, because the five-year window is closing through 2026.
- After: issue the one-page purchasing, payment and verification policy within five working days, while the session is still current.
- After: diarise a review for the first tax year commencing after 1 October 2027, when the turnover-based apportionment method begins.
What to hand out
Give every attendee something to take away, because the room is rented for two hours and the rules last longer than that.
- The instrument table from the what changed section, with the five dates.
- The three supplier risk indicators on a single card.
- The AED 375,000 bank-confirmation test, with the registration threshold distinction written underneath it.
- The e-invoicing phase table with the company's own phase circled.
- The penalty tables, side by side on one page.
- The draft one-page policy, with blanks for names, thresholds and dates.
If you would rather run the session as part of a wider compliance programme, our Tawjeeh labour-law orientation classes and our Tasheel labour transaction coordination sit alongside the room, and our PRO services team handles the government-side work that follows a licence or visa change.
Why a business centre room beats a hotel for this
For a compliance briefing, the venue requirements are unglamorous: a projector, a whiteboard, reliable WiFi, seating that fits the whole team, and a booking you can end after two hours. That is exactly what a Tawtheeq-registered business centre in Mussafah M4 is built for, five minutes from the MOHRE centres and with parking on site.
The Musaffah room also keeps the session close to where your team already works, which matters more than a prestigious address for an internal briefing. If you are weighing a virtual office against a physical room for the wider team, our virtual office options cover the address and mail side while the training room covers the people side.
Frequently Asked Questions
What are the new UAE VAT rules from 1 October 2026?
Most of the amendments in Cabinet Decision No. 149 of 2026 apply from 1 October 2026. The changes your team will feel first are: input VAT can be blocked on supplies paid, or intended to be paid, in cash above a threshold the Minister of Finance will set in a separate decision; VAT on staff accommodation is recoverable through the labour-law exception only where MoHRE makes the housing mandatory; and the VAT treatment of bundled, composite supplies is now judged by the economic substance of the supply. The revised input tax apportionment method is deferred to the first tax year starting after 1 October 2027.
Is input VAT recoverable on cash payments in the UAE?
Not where the supply exceeds the threshold the Minister of Finance will prescribe, and the consideration is paid or intended to be paid in cash. As of 6 October 2026 that threshold had not been published, so the practical step today is to identify every supplier you pay in cash, move those payments to a corporate bank account where you can, and keep a written record of why any cash payment was necessary. The Ministry's stated purpose is to strengthen compliance and mitigate the risk of tax evasion.
What is supplier verification under FTA Decision No. 13 of 2026?
It is a documented due-diligence duty that applies the first time you deal with a supplier, and again if twelve months have passed. You check the supplier's identity documents against official databases, confirm the individual authorised to represent the supplier, and confirm the supplier has an actual place of business consistent with its claimed activity. You then assess three risk indicators: a change of address, a change of key personnel, and transactions that are disproportionate to the size and history of the business.
What is the AED 375,000 threshold in the supplier verification rules?
Where the annual supplies you receive from a single supplier exceed AED 375,000, you must additionally obtain unqualified written confirmation from a bank authorised in the UAE that the supplier holds an account there, and review public reviews and media coverage of that supplier. Do not confuse this with the AED 375,000 mandatory VAT registration threshold — the two numbers are coincidentally the same, but one is a registration trigger and the other is a verification trigger.
When is e-invoicing mandatory in the UAE?
The pilot programme and voluntary onboarding opened on 1 July 2026. Mandatory implementation is phased by revenue: businesses with annual revenue of AED 50 million or more had to appoint an Accredited Service Provider by 31 July 2026 and go live on 1 January 2027; businesses below that threshold appoint an ASP by 31 March 2027 and go live on 1 July 2027; government entities follow on 1 October 2027. PDF, Word, images and scanned copies are not e-invoices.
Can I recover VAT on staff accommodation in the UAE?
Through the labour-law exception, only where a Ministry of Human Resources and Emiratisation decision or directive makes the housing mandatory. For other employee benefits provided under a contract or a documented policy, recovery follows the cases and conditions the Federal Tax Authority sets. Review employment contracts, HR policies and accommodation arrangements, and the rationale behind each benefit, before you recover the input tax.
How much does it cost to train a team on VAT in Abu Dhabi?
The 49-seat training room in Mussafah M4, Block 10, starts from AED 250 per hour, so a two-hour VAT session costs AED 500 from that rate. At full capacity that is about AED 10.20 per person; at twenty attendees it is AED 25.00 per person. Projector, air conditioning, high-speed WiFi and a whiteboard are included, and same-day booking is available on request. Catering, printing and stationery are not part of the hourly rate.
Is this article tax advice?
No. It is a plain-language summary of publicly announced UAE VAT changes and a practical guide to briefing your own team. The cash-payment threshold and several implementing details had not been published as of 6 October 2026, so confirm every figure and date against the Ministry of Finance and Federal Tax Authority before you act on it, and take structured advice from a tax professional for your own position. Tasreea's VAT services team can help with registration, filing and FTA correspondence, but this post does not replace that advice.
Book the room and run the session
Tell us your headcount and your preferred date and we will confirm availability for the 49-seat training room in Mussafah M4 from AED 250/hour, with projector, air conditioning, high-speed WiFi and a whiteboard. Same-day booking is available on request, and we will hold the slot while you decide.
Or call +971 2 552 3934 or email enquiries@tasreea.ae. Sunday to Thursday, 9 AM to 6 PM.